

In a transaction that underscores the intensifying appetite for high-margin, niche travel assets, Odyssey Traveller, an Australian-founded stalwart of the educational tourism sector, has been acquired by a United States-based investor for $849,600.

The deal, transacted via the global asset marketplace Flippa, represents a significant exit for a business that has spent 36 years cultivating a monopoly on the “curious senior” demographic. The acquisition signals a sophisticated play into the “silver economy,” where experience-led travel is outperforming traditional leisure segments.

400,000+ Weekly Active Buyers
20+ Multi-language Brokers
Seamlessly Negotiate and Receive Offers
Integrated Legal, Insurance, Finance and Payments
The Asset: A Legacy of Intellectual Arbitrage
Founded in 1983, Odyssey Traveller carved out a defensible moat by eschewing mass-market tourism in favour of small-group, educational itineraries. Operating approximately 25 to 30 tours annually, the business focuses on “in-depth” experiences, ranging from archaeology to art history, tailored for the 65+ cohort.
The financial profile of the firm at the time of sale was particularly compelling for mid-market private equity and individual investors alike:
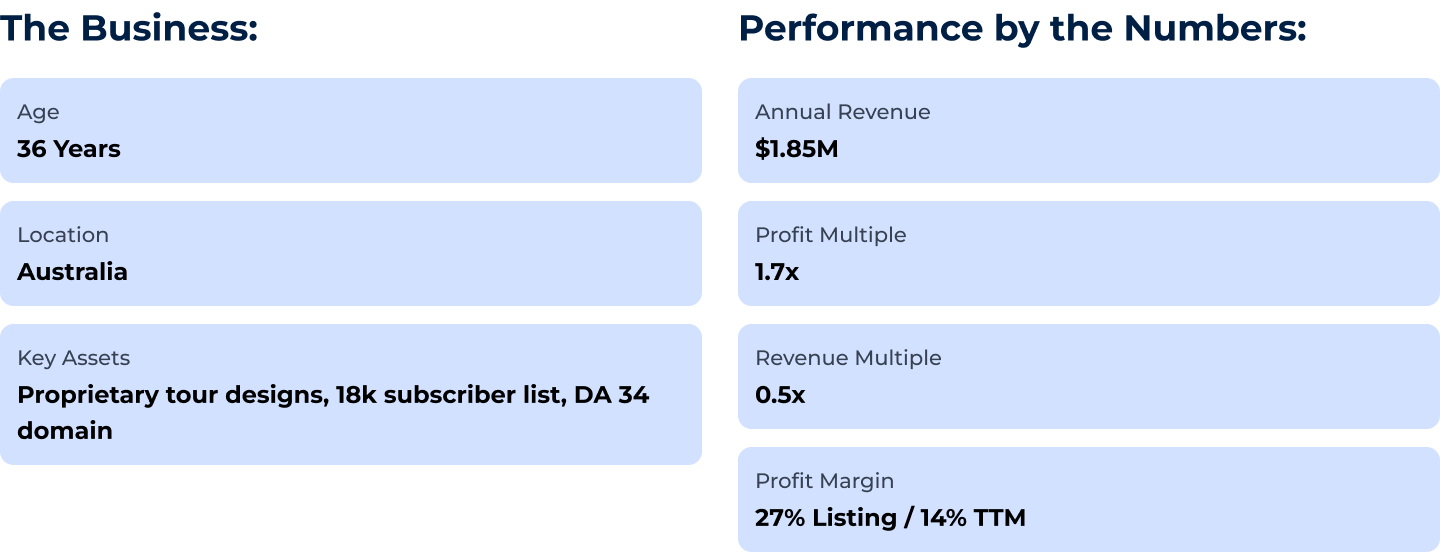
- Annual Revenue (TTM): AUD $1,988,314 (approx. USD $1.86M)
- Annual Profit (TTM): AUD $271,795 (approx. USD $496,816)
- EBITDA Margin: 14% (Normalized for industry lean-staffing models)
- Direct-to-Consumer (DTC) Efficiency: 90% of bookings occur directly via the website, bypassing the 10-15% commission leakage typically associated with third-party travel agencies.
The Strategic Rationale: Why the Deal Closed
The $849,600 price tag reflects not just a multiple of earnings, but the value of proprietary intellectual property and digital dominance.
1. High-Value Unit Economics
With an average ticket price of AUD $16,000 per traveller, the business benefits from a premium positioning. The operational model—utilising casual tour leaders and outsourced technical support—allows for a “lean” cost structure that requires only 2 to 4 hours of weekly owner involvement.
2. SEO and Digital Authority
In an era where customer acquisition costs are skyrocketing, Odyssey’s Domain Authority of 34 and its library of high-ranking SEO content provide a sustainable inflow of organic leads. The sale included a high-intent email list of 18,000 subscribers, a critical asset for driving repeat bookings in the senior demographic.
3. Geographic Arbitrage
The buyer, located in the United States, is well-positioned to leverage the existing Australian infrastructure to capture a larger share of the North American market. By acquiring an Australian-based operator with established ground-handler relationships, the buyer gains an immediate foothold in the Asia-Pacific “inbound” sector, which remains a key growth lever.
Transaction Summary
The Outlook: Scaling the “Silver Wanderer”
The experiential travel sector in 2026 is increasingly defined by “purpose-driven” journeys. For the new owners, the growth path is clear: monetizing the existing content library more aggressively and re-launching the inbound tour products for the New Zealand and Australian markets.
As the founder transitions into retirement, the “turn-key” nature of Odyssey Traveller—bolstered by a 2025 infrastructure refresh—serves as a blueprint for successful M&A in the digital-first service economy. For investors, the message is clear: longevity and niche authority are the ultimate hedges against market volatility.
400,000+ Weekly Active Buyers
20+ Multi-language Brokers
Seamlessly Negotiate and Receive Offers